Benafica is a health benefits and insurance company that helps employers offer flexible, tax-free health reimbursement plans instead of traditional group health insurance.

Contact Us
6701 Upper Afton Rd. Ste. 200, St. Paul, MN 55125

ICHRA · CHOICE Arrangements

ICHRA Administration for Any Size Employer

A successful ICHRA takes more than a platform.

Benafica brings the technology, administration, compliance, payment infrastructure, and people to make it work.

As of September 3, 2026: The Individual Coverage Health Reimbursement Arrangement (ICHRA) has a new name: CHOICE Arrangement.

CHOICE stands for Custom Health Option and Individual Care Expense

A CHOICE Arrangement is the same thing as an ICHRA. It’s just got a new name!

For Employers

ICHRA with Benafica

We’ve been doing ICHRA since the very beginning.

When employers choose Benafica, they get more than a platform. They get a team that knows ICHRA inside and out. We make the transition straightforward, keep employers and brokers informed, and provide real human support to employees throughout the process. Our hands-on approach means less guesswork, fewer headaches, and a benefits experience employers can feel good about year-round.

Northline Manufacturing

The Model

Monthly Allowance: $520
Employees: 240

Individual Plans Available: 38
Carriers: 5

Group plan — 2027 renewal

$158,400

$38,400

ICHRA at $520 per employee

$124,800

$31,200

(-21%)

Employer

Employees

Illustrative model. Actual figures depend on your counties, workforce and current rates.

If you have fewer than 50 employees and want a simpler benefit with a fixed ceiling, compare this against a QSEHRA.

Benefits Made Simple

How it Works:

1

Employer sets monthly allowance

Decide how much to contribute each month toward each employee’s healthcare costs, based on local individual market plans.

2

Employees choose coverage

Employees shop, compare, and enroll in an individual plan that fits their needs — right inside the BEN360 platform.

3

We enroll and set up payments

We process enrollment behind the scenes and set up monthly premium payments so coverage stays active without extra work on your end.

4

Ongoing administration

New hires, terminations, and qualifying life events are all handled in one place, with support year-round.

End-to-end ICHRA support

We Handle the Administration

Running an ICHRA means handling plan documents, employee notices, coverage substantiation, premium payment and reconciliation, mid-year changes, payroll treatment, and year-end reporting.

Administration Includes:

*Benafica provides administrative and reporting support but does not provide tax or legal advice. Employers remain responsible for reviewing, approving, and filing their required tax forms and should consult their tax advisor regarding their specific reporting obligations.

For Brokers

Expand Your Benefits Strategy

An ICHRA isn’t a product that replaces what you sell. It’s a second answer for the client whose renewal came back at eighteen percent. It also opens groups you couldn’t write before:

Benafica handles the administration. You keep the relationship.

an employee benefits broker talking to a client in office setting
For Employees

More CHOICE in How You're Covered

employee 1
$567 per month 100%
employee 2
$832 per month 100%
employee 3
$1,129 per month 100%
employee 4
$955 per month 100%
You choose your coverage
Shop for an individual health plan that fits your needs, budget, doctors, prescriptions, and preferred coverage.
Your allowance helps pay for coverage
Learn how your employer’s monthly contribution works and what expenses may be eligible for reimbursement.
Coverage that fits your needs
Individual coverage gives you access to a wide range of plan options, including different carriers, networks, and coverage levels.
Keep your coverage if you change jobs
Your individual health plan belongs to you, although your employer’s ICHRA contribution ends when your employment ends.
Life changes? Your coverage can too
Learn how marriage, having a baby, losing other coverage, moving, and other qualifying life events can affect your options.
Real people when you need it
Get year-round support from a real person, not a chatbot. Benafica’s licensed benefits counselors can help you understand your options and find coverage that works for you.
End-to-End ICHRA Support

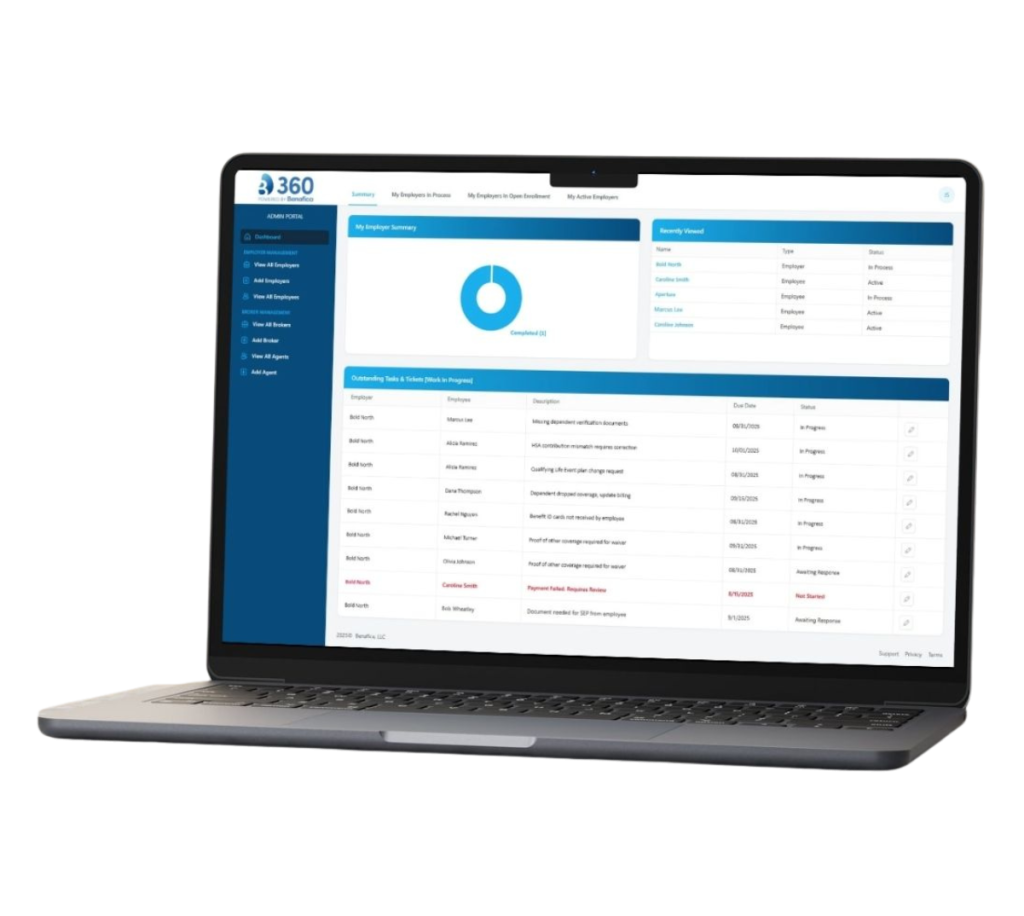
Meet BEN360: Our ICHRA Platform

FAQ

ICHRA Frequently Asked Questions

Still have questions about ICHRA? We’re here to help.

Benafica provides ICHRA administration nationwide, serving employers across all 50 U.S. states.

Employers of any size can offer an ICHRA. You need to have at least one W-2 employee. An ICHRA typically starts to make more sense for employers with 5 or more employees.

Most employers start by looking at current benefits spend and local individual-market premiums for their employees’ ages and locations. From there, they choose an allowance strategy. With a flat-dollar strategy, you offer a flat amount to all your employees (or employees across a group). With an age-banded strategy, you offer a percentage of a targeted plan’s premium, such as 75% of a gold plan. Learn more about contribution strategies.

Yes. ICHRA can either be used to fully replace your traditional group health plan or you can offer it alongside a group plan for specific employee classes. For example, you might offer a group plan to full-time employees and an ICHRA to part-time employees.

Employee classes let employers offer different allowance amounts and eligibility rules to defined groups, such as full-time, part-time, salaried, hourly, different locations, etc. There are 11 different classes and they are set by IRS regulations. Employees in the same class must be treated equally. Learn more about ICHRA employee classes.

Yes. An ICHRA can satisfy the ACA employer mandate as long as premiums are considered “affordable” for your employees. Learn more about affordability for ALEs.

Yes. You don’t have to wait for annual open enrollment to start an ICHRA. Offering an ICHRA opens up a special enrollment period for your employees. Read our blog article on this for more.

Unused funds stay with the employer. If employees choose a plan that’s less expensive than your contribution, the extra funds stay with the company. You can also choose to reimburse out-of-pocket medical expenses with leftover funds.

ICHRA is available nationwide, but the experience varies with the strength of each state’s individual market. A handful of states have also begun adding their own ICHRA incentives. See what states are doing.

The allowance ends per your plan’s terms — but the employee’s health plan is theirs, not yours, so their coverage continues if they keep paying for it. There’s no COBRA-style group continuation to administer.

An ICHRA and a Premium Tax Credit (PTC) generally can’t be used together. If an ICHRA is considered affordable, an employee who accepts it isn’t eligible for a Marketplace Premium Tax Credit. If the ICHRA is unaffordable, the employee can choose between accepting the ICHRA or opting out and using the Premium Tax Credit instead. Read our blog article on this for more.

Setting up an ICHRA can happen in a matter of days when we have the information we need to get started. The bigger consideration is timing. Employers need to meet required notice periods and give employees enough time to understand their new benefit, review their coverage options, and choose an individual health plan.

Starting early gives everyone more time to prepare and helps make the transition to an ICHRA as smooth as possible.

Absolutely. Many employers keep their broker for overall benefits strategy while the ICHRA itself is administered by a TPA. We work alongside brokers regularly rather than replacing them.

On the Blog

Latest ICHRA Articles

ACA Affordability rate paycheck example
ACA Affordabe Care Act

IRS Raises 2027 ACA Affordability Rate

The IRS has raised the ACA affordability rate for 2027 to 10.22% of household income, up from 9.96% and above 10% for the first time since the employer mandate took effect. Here’s what the new safe harbor limits mean for your contribution strategy.
Read More →
Man at a desk looking at laptop calculating premium tax credits
ACA Affordabe Care Act

How ICHRA and QSEHRA Work with Premium Tax Credits

What happens to an employee’s premium tax credit eligibility when they get offered ICHRA or QSEHRA dollars? Learn more about how each HRA coordinates with premium tax credits and things you should consider as an employer before you implement a plan.

Read More →
Get in Touch

Ready to Offer Better Benefits?

We’ll build a side-by-side comparison against your current plan using your actual census, so you can see the real numbers before you decide anything.

Get a Quote